

Atlas - Rewards Credit Card

- 32.44K Reviews
- 4.6
- Downloads
- 1,000,000+
Our take on Atlas - Rewards Credit Card from Appgk
I approached Atlas - Rewards Credit Card as a finance app for people who want to manage credit-building and cash-back activity from a phone rather than treating those tasks as occasional paperwork. My first impression was that its purpose is easy to understand: it combines a rewards-focused card experience with tools intended to help users build credit. That combination can be useful, but it also means the app deserves a more careful look than a simple cash-back wallet. Money apps need to be understandable when you are tired, distracted, or trying to make a decision quickly.
Developed by Exto Inc., Atlas is free to download and is rated for Everyone. It has become a widely used option, with more than a million installs and a 4.6 average from roughly 174 thousand ratings. Those figures suggest that it has reached well beyond a small group of finance enthusiasts, although popularity alone does not tell me whether it suits every user. My review focuses on how clearly the experience works, especially for people with different abilities, different levels of financial confidence, and different everyday circumstances.
How Atlas handles everyday finance tasks
Readability and navigation
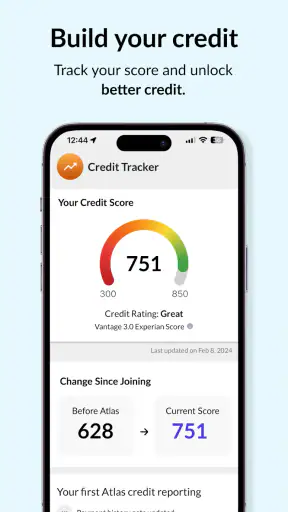
The strongest part of the concept is the way it gives two related goals a shared home. Instead of using one service for rewards and another for credit-building information, I can think of Atlas as a single place to check activity and keep an eye on progress. That reduces the mental switching that often makes personal finance feel harder than it needs to be. The store summary, “Earn cash back. Build credit,” is brief, but it accurately captures the two reasons someone would open the app.
In practical use, a finance app should answer three questions quickly: what happened, what do I need to do, and what might happen next? Atlas is most useful when I approach it with those questions in mind. I would open it before making a planned purchase to confirm that the card is the right payment choice, then return later to review the transaction and any related reward information. This is more helpful than checking a balance without understanding how that balance fits into a broader credit routine.
Best Parts of Atlas - Rewards Credit Card
Things to Keep in Mind About Atlas - Rewards Credit Card
The navigation is easier to evaluate when I separate occasional tasks from repeated ones. A person who checks an account once a month may find the app straightforward, while someone who wants to monitor every purchase may need a more disciplined routine. I recommend choosing one regular review moment, such as after grocery shopping or at the end of the week, rather than opening the app constantly. That habit makes the information more meaningful and avoids turning every small transaction into a source of worry.
Readability is not only about font size. It also depends on whether labels explain themselves and whether important financial information is visually separated from promotional or reward-oriented content. Atlas benefits when its screens make the distinction between spending, available credit, rewards, and credit-building progress obvious. If those ideas are presented too close together, a new user can easily assume that cash back and credit improvement are automatic results of the same action. They are related goals, not interchangeable ones.
News and Features Related to Atlas - Rewards Credit Card

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
For users who are new to credit, the wording matters even more than the number of screens. A clear explanation of an action is more valuable than a polished dashboard that leaves the user guessing. I would take time to read each confirmation and review the details of an unfamiliar transaction rather than relying on a quick glance. That is a useful safety habit in any financial app, but especially in one that encourages users to think about both rewards and credit history.
Motor and sensory considerations
Atlas is designed for phone use, which makes it convenient but also places the whole experience inside a small touch interface. Users with limited dexterity may find repeated tapping, scrolling, or precisely selecting small controls tiring. My practical advice is to use the app when you have a stable surface and enough time to verify each action. A rushed tap is more costly in a finance app than in a social or entertainment app.
Don't want to read the full review?
People with vision-related needs should pay attention to whether the text and contrast remain comfortable on their particular device. I would not assume that a generally clean interface works equally well for everyone, because display size, brightness, system text settings, and visual fatigue vary widely. Enlarging system text can improve comfort, but it may also cause some screens to show less information at once. That creates a trade-off: larger text can be easier to read, while a compact overview may require more scrolling.
Users who rely on screen readers or other assistive technologies should test the most important route first: opening the app, locating the current account information, reviewing a transaction, and finding the relevant action without depending on color or position. I cannot treat the app as universally accessible simply because it is available on a mobile device. The real question is whether each control has a clear spoken label and whether the order of information makes sense when visual layout is removed.
Screenshots
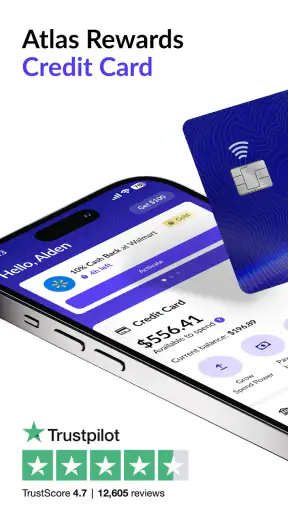
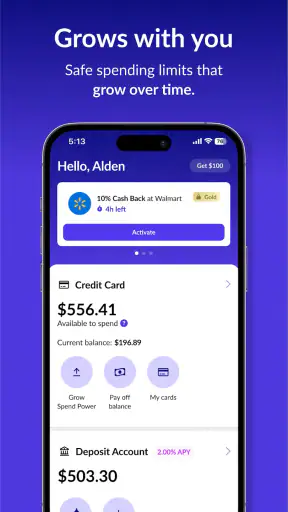
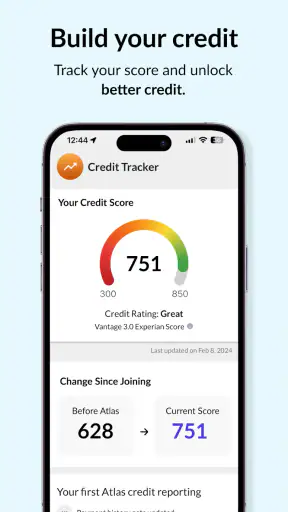
Sensory comfort also matters. Financial notifications can be useful reminders, but frequent alerts may become distracting for someone who is sensitive to interruptions or already receives many messages. I prefer a deliberate notification setup: keep alerts that help identify important account activity, and silence anything that does not support a decision I actually need to make. The best arrangement will depend on the person, but the principle is consistent—notifications should reduce uncertainty, not create a stream of low-value noise.
For users with cognitive or attention-related needs, Atlas is easier to manage when it becomes part of a simple checklist. I would avoid opening several financial apps at once, compare one transaction at a time, and write down any question before leaving the screen. This may sound basic, but it prevents a common problem in finance tools: confusing a reward display with money that is immediately available to spend, or mistaking a credit-related indicator for a guarantee of a particular outcome.
Situational access in real life
The most convincing use case is an ordinary purchase made during a busy day. Imagine buying household items while managing a child, carrying bags, and trying to stay within a budget. In that situation, Atlas can be useful before the purchase if I already know how I intend to use the card, and after the purchase when I have a quiet moment to review what happened. It is less suitable as a tool for making complicated decisions while standing in a checkout line.
Another realistic scenario is a user who has never had much experience with credit. That person may appreciate having rewards and credit-building information together, because the app gives a reason to return and observe financial behavior. The danger is assuming that regular app activity itself builds credit. The user still needs to understand the card’s terms, use it responsibly, and treat any credit-related progress as something that depends on account behavior rather than simply installing the application.
Atlas can also fit someone who prefers a mobile-first routine. If you already review spending on your phone and dislike paper statements or scattered services, a single app may feel less burdensome. I would use it alongside a basic monthly budget, not instead of one. Rewards can make a purchase feel more attractive, but a reward is not a reason to spend beyond what you can comfortably manage.
Situational access changes when connectivity, battery life, privacy, or time become problems. A person traveling, working in a noisy environment, or sharing a device may not be able to review financial information comfortably. I would avoid making sensitive account decisions in public and would postpone anything that requires careful reading until I have privacy. The convenience of a phone should not pressure anyone into handling financial information in an unsuitable setting.
The app’s Everyone age rating makes it broadly approachable from a content perspective, but that should not be confused with being appropriate for every financial situation. A young or inexperienced user may still need help understanding credit, repayment responsibilities, and the difference between rewards and available funds. Atlas can support a learning routine, but it should not replace guidance from a trusted adult or qualified financial professional when the consequences of a decision are significant.
How it compares with usual alternatives
The usual alternative is to rely on a traditional banking app for account information and a separate rewards program for cash back. That arrangement may offer more familiar banking tools, especially for people who want all of their accounts displayed together. Atlas has a clearer appeal when the main goal is to combine a card-centered rewards experience with attention to credit-building rather than to replace a full-service bank.
A spreadsheet is another alternative. Spreadsheets offer flexibility and can be excellent for users who want to categorize every expense, compare months, or create custom formulas. They are less convenient for checking card activity on the go, and they require manual discipline. Atlas is the better fit when I want a ready-made mobile workflow; a spreadsheet is better when I want complete control over how information is organized.
Credit-monitoring services may provide a broader view of credit information, while a card app can feel closer to the spending behavior that affects the user’s routine. I would not choose Atlas solely because it mentions credit-building. I would choose it if the card and rewards structure match my needs and if I am willing to learn how the account works. Someone who already has a carefully managed credit system may gain more from a dedicated budgeting or monitoring tool.
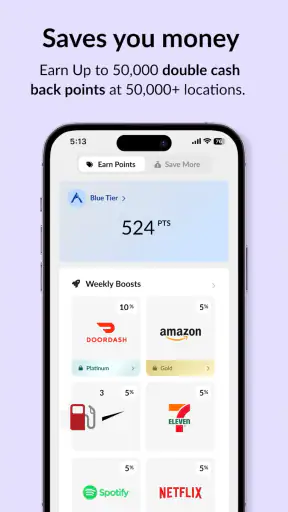
There is also a psychological difference between Atlas and a plain banking app. Cash-back language can make the experience feel rewarding, which may encourage regular engagement. That can be positive if it leads to better review habits. It can be counterproductive if it encourages unnecessary purchases. My rule would be simple: decide what to buy first, then consider whether the reward is useful. Never reverse those steps.
Remaining barriers and friction
The biggest barrier is not necessarily navigation; it is interpretation. Credit products contain terms that can be easy to misunderstand, and a friendly mobile interface cannot remove that complexity entirely. Before relying on Atlas, I would read the account terms carefully and make sure I understand payment timing, fees, reward conditions, and what information is being shown. Those details matter more than a smooth dashboard.
Another limitation is that a phone interface can encourage quick confirmation. When a screen presents a reward or progress indicator, it may feel like the app is giving an immediate verdict on financial health. I would resist that impression. A single week of activity cannot tell the whole story, and a positive reward display does not mean that spending is affordable. Atlas works best as a regular checkpoint, not as a substitute for a complete financial plan.
Accessibility can also remain uneven from one person to another. A user may be comfortable with touch controls but struggle with small text; another may read the screen easily but find the sequence of actions confusing. People who need keyboard navigation, extensive screen-reader support, or highly customized visual presentation should test the core workflow early rather than assuming the app will match their setup. If it creates repeated friction, a more established banking tool or a desktop-based system may be the better choice.
Privacy is another reason to be deliberate. Finance apps require a higher level of trust than many everyday utilities. I would keep the phone protected, avoid sharing login details, and review account activity regularly. These are not special Atlas tricks; they are sensible habits whenever an app is connected to spending or credit information. The more convenient the app becomes, the more important it is to maintain those boundaries.
Version 6.0.10 is the current version, and the app supports devices running Android 7.1 or later. That broad compatibility is helpful for people who keep an older phone, but an older device may still provide a less comfortable experience because of screen quality, speed, battery condition, or system settings. I would judge performance on the actual phone being used, especially if the owner depends on larger text or assistive features.
Who should use it, and who should look elsewhere?
I would recommend Atlas to someone who wants a focused, mobile-first way to engage with rewards while paying attention to credit-building. It is particularly suitable for a person who benefits from one recurring review routine and who is prepared to read the terms instead of treating the reward message as the whole product. The free price removes an obvious entry cost, but responsible use still depends on the account’s conditions and the user’s spending habits.
I would be more cautious about recommending it to someone who wants a complete household finance center. If your priority is bill scheduling, detailed budgeting across several banks, investment tracking, or extensive desktop reporting, a broader financial platform may serve you better. Atlas has a specific purpose; its value comes from that focus, not from trying to be every financial tool at once.
I would also suggest looking elsewhere if rewards tend to make you spend impulsively, or if you need a highly customized accessibility experience and the core screens do not work comfortably with your device settings. No amount of cash back compensates for confusion, missed payments, or an interface that prevents you from checking important information independently.
My inclusive verdict
After looking at Atlas through the lens of readability, physical interaction, sensory comfort, and real-world circumstances, I see a useful but purpose-specific finance app. Its clearest strength is the connection between cash-back motivation and credit-building awareness. That pairing can encourage a regular review habit, especially for users who prefer handling money from a phone and want a less fragmented routine.
Its limitations are equally important. The app cannot make credit concepts simple by itself, and a rewards-focused presentation can be misunderstood if the user does not separate incentives from affordability. Accessibility will also depend on the individual device and assistive setup, so I would test the essential workflow before committing to it as a primary financial tool.
My final recommendation is measured: try Atlas if you want a dedicated mobile experience around rewards and credit-building, and approach it with a written spending plan and a calm review routine. I would not use it as my only source of financial understanding, but I can see why it has earned a strong 4.6 average across a large user base. For the right person, the best feature is not the promise of cash back; it is the chance to turn occasional checking into a more intentional habit.
Atlas - Rewards Credit Card FAQ
What is the Atlas Rewards Credit Card, and how does it work?
Atlas Rewards Credit Card is a credit-building and rewards-focused card designed for eligible users who want to manage everyday spending while potentially improving their credit profile. After approval, you can use the card for purchases wherever the network is accepted, monitor activity through the companion app, and make payments electronically. Features, rewards, fees, and approval terms can vary, so review the current cardholder agreement before applying.
Can Atlas Rewards Credit Card help me build or improve my credit score?
Atlas may help establish or strengthen your credit history when the account is used responsibly and payments are made on time. The benefit depends on whether account activity is reported to the relevant credit bureaus, your existing credit profile, utilization, and payment behavior. No card can guarantee a higher score. Before downloading or applying, check the app’s current reporting policy and understand how late payments may affect your credit.
What rewards can I earn with the Atlas Rewards Credit Card?
The card may provide rewards for eligible purchases, but the exact earning rates, categories, redemption options, limits, and expiration rules should be confirmed in the latest Atlas terms. Some transactions may not qualify, including cash advances, fees, balance transfers, or returned purchases. Open the app after approval to review your rewards balance and read the applicable program conditions before relying on rewards for a specific purchase.
Are there fees or other costs associated with Atlas Rewards Credit Card?
Potential costs can include an annual or membership fee, interest charges, late-payment fees, cash-advance costs, foreign-transaction fees, or other account-related charges, depending on the offer and your location. The app itself may be free to download, but that does not mean the credit product has no cost. Carefully compare the disclosed APR, fee schedule, billing cycle, and payment requirements before accepting an offer.
What information and permissions does the Atlas app require?
To apply for or manage the card, Atlas may request personal details such as your name, address, income information, identification data, and banking or payment information. The app may also use device, security, and notification permissions to support login, verification, alerts, and account management. Only install it from an official store, review its privacy policy, enable strong authentication, and avoid sharing passwords or verification codes.











